
Is Kentucky Good for Retirees? 2026 Pros, Cons & Tax Math
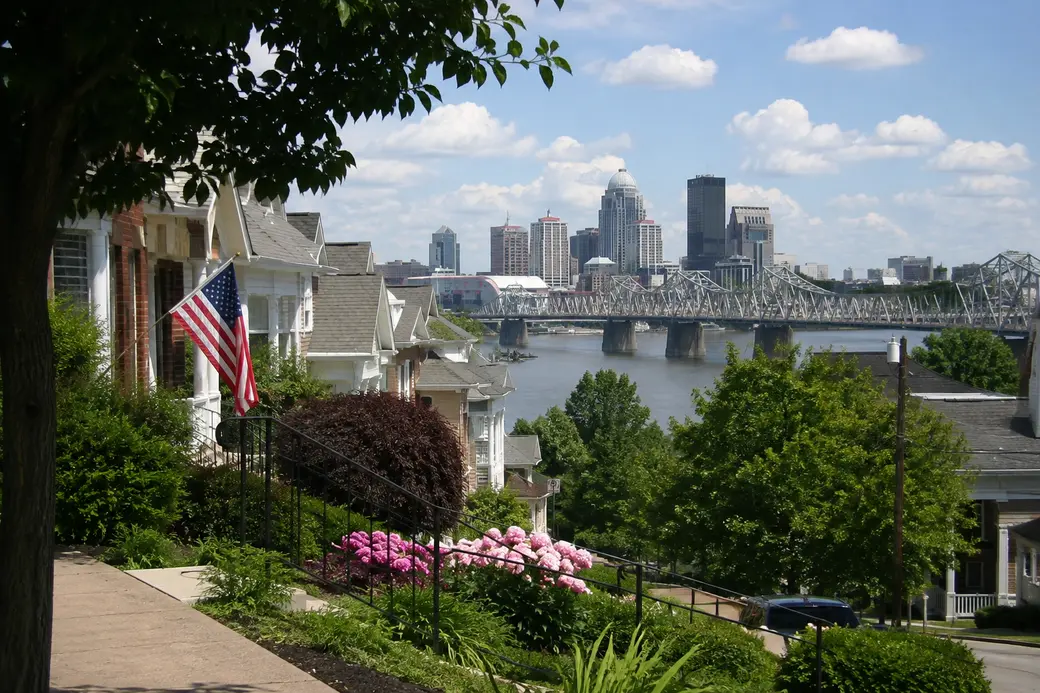
Relocation & Retirement Planning · Louisville & Southern Indiana
Is Kentucky a Good State to Retire In? Pros & Cons
A look at housing costs, taxes, and healthcare access for retirees weighing Louisville, Shepherdsville, Elizabethtown, and Southern Indiana.
Yes, for most retirees with pension or IRA income. Kentucky doesn't tax Social Security, leaves the first $31,110 per person of pension, IRA and 401(k) income off your return, and taxes the rest at 3.5% (2026). A single retiree, 65+, with $40,000 of pension income pays about $311 in Kentucky income tax, vs. about $1,881 across the river in Clark County, Indiana. Homeowners 65+ also get the $49,100 Kentucky homestead exemption, worth about $614 a year in Louisville.
The catch: property taxes run higher than in Southern Indiana, where a 1% homestead cap applies, and healthcare access is strong in the Louisville metro but thinner in rural parts of the state. If you'll live mostly on Social Security, Southern Indiana's lower property tax can come out ahead.
Retirement changes the way you should think about where you live. During your working years, a higher housing payment may be manageable because your income can still grow. In retirement, the equation is different: taxes, insurance, healthcare, maintenance, and the amount of equity tied up in your home all carry more weight in your financial flexibility.
Some national rankings have placed Kentucky near the bottom for retirement, largely on healthcare and quality-of-life measures. That single ranking rarely reflects what a retiree considering Louisville, Shepherdsville, Elizabethtown, or Southern Indiana actually needs to know. The more useful question is:
Which location gives me the best combination of housing cost, taxes, healthcare access, and long-term financial flexibility?
Comparing Louisville against Southern Indiana, Shepherdsville, or Elizabethtown for retirement? I can walk through the numbers with you.
Talk With TamaraIs Kentucky a Good Place to Retire?
Kentucky can be a good state for retirement when affordability and tax treatment are priorities. Here is the current picture at a glance:
| $31,110 Max KY pension & retirement income exclusion | $49,100 KY senior homestead exemption, 2025–2026 | 0% KY state tax on Social Security income |
| $280,000 Louisville median sold price, Sept 2026 | $205,600 KY statewide median home value, 2020–2024 | 480+ Norton Healthcare locations, KY & Southern Indiana |
The biggest considerations on the other side of the ledger: healthcare access varies significantly by location, Kentucky still has a state income tax, property taxes depend on local taxing districts, and a national ranking rarely reflects the specific advantages of the Louisville region.
Why Kentucky Can Be Attractive for Retirees
1. Housing affordability can stretch retirement savings
A retiree who owns a $250,000 home outright is in a very different financial position than someone carrying a $450,000 mortgage, even with similar retirement income. Kentucky's statewide median value of owner-occupied housing was $205,600 for 2020–2024, according to the U.S. Census Bureau, with median monthly owner costs of $1,433 for homes with a mortgage. Those are statewide figures, so treat them as a starting point rather than the price of a typical Louisville home.
Louisville itself is a useful example of why local numbers matter more than statewide averages. The median sold price in the city of Louisville was $280,000 in September 2026, and homes sold in about 27 days on average (Flexmls). For where the local market stands right now, see the October 2026 Louisville market update.
For retirees, the real question isn't whether a home is "affordable" on paper. It's what the home will cost every month after you retire, once you add property taxes, homeowners insurance, utilities, maintenance, HOA fees, transportation, and future repairs to the mortgage. A $250,000 house with expensive upkeep can end up costing more over time than a $275,000 home that's newer and more efficient to run.
2. Kentucky's tax treatment can benefit some retirees
Kentucky's individual income tax rate is 3.5% for 2026, but retirees may qualify for meaningful exclusions. The state does not tax Social Security benefits, and it allows an exclusion of up to $31,110 of qualifying pension and retirement income under current rules (military retirees with pre-1998 service may exclude more). See how Kentucky taxes retirement income in 2026 for worked examples.
A retiree drawing income from Social Security, a pension, and IRA or retirement-account distributions shouldn't assume all three are treated the same way for Kentucky tax purposes. The type and amount of each income source matters, which is exactly why a retirement location decision should be built on an actual household tax analysis rather than a generic "retirement-friendly state" list.
3. Kentucky offers a senior homestead exemption
Kentucky homeowners who are at least 65, or who meet the state's disability requirements, may qualify for the Kentucky homestead exemption. For the 2025–2026 tax periods, that exemption is $49,100 (about $614 a year off a Louisville bill), applied against the assessed value used to calculate property taxes. It's meaningful, but it doesn't eliminate property taxes entirely; local taxing districts still shape the final bill, so the actual number should be checked for any specific property under consideration.
4. Louisville provides access to a large healthcare network
Healthcare becomes one of the most important location factors as retirement progresses, and it's an area where home prices alone can produce a misleading decision. Norton Healthcare operates six hospitals in Louisville and three in Southern Indiana, with more than 480 locations across the two states. That level of access isn't uniform statewide; a rural property several hours from major medical services is a very different decision than a home inside the Louisville metro.
Worth checking directly for any location under consideration: distance to a preferred hospital, specialist and primary-care access, emergency care, pharmacy access, transportation, and future mobility needs. CMS's Care Compare system also allows research on individual hospitals rather than relying on broad state rankings alone.
What Are the Downsides of Retiring in Kentucky?
Kentucky isn't a perfect retirement destination. Some 2026 national rankings have placed it near the bottom among states for retirement, generally weighing affordability alongside healthcare and quality-of-life factors. That creates an important distinction: Kentucky can be financially attractive without being the highest-ranked state overall.
Healthcare varies by location
Access is much stronger in metropolitan areas than in some rural parts of the state. If healthcare is a top priority, evaluate the specific community rather than the state as a whole. Louisville and its surrounding metro offer considerably different access than a remote rural location.
Property taxes aren't the whole housing cost
A common mistake is comparing property-tax rates while ignoring the rest of the housing budget. A more useful formula:
Total housing cost = taxes + insurance + maintenance + utilities + mortgage + HOA
A lower purchase price doesn't automatically create a lower long-term cost.
Weather and maintenance matter
Kentucky has four distinct seasons, which many retirees enjoy, but it also means budgeting for heating, cooling, roof upkeep, gutters, landscaping, and weather-related repairs. A large property that feels manageable at 60 can feel very different at 75, which is why retirement housing should be evaluated for future usability rather than current appeal alone. For ideas on updates that hold their value over time, see this look at 2026 renovation trends in Louisville.
Louisville vs. Southern Indiana for Retirement
For someone considering the Louisville region, the decision isn't necessarily Kentucky versus a state hundreds of miles away. Communities such as Jeffersonville, New Albany, and Clarksville sit across the Ohio River, giving retirees another housing and tax comparison within the same broader metro.
Neither state taxes Social Security. Every Indiana county adds its own income tax (Floyd County: 1.89%). Rate alone doesn't determine total cost; see the comparison below.
On property tax, Indiana caps homestead bills at 1% of gross assessed value, and homeowners 65+ can get an Over 65 Credit of up to $150 (see Indiana's Over 65 credit). On a $350,000 home, that usually leaves a Southern Indiana bill about $700 a year lower than Louisville's, even after Kentucky's $49,100 exemption. So the real comparison isn't "which state has lower taxes," it's the total annual cost of each specific location. For a deeper side-by-side, see this full Kentucky vs. Indiana retirement comparison.
| Factor | Louisville / Kentucky | Southern Indiana |
|---|---|---|
| State income tax | 3.5% in 2026 | 2.95% in 2026, plus county tax (2.0% Clark, 1.89% Floyd) |
| Social Security | Not taxed by KY | Not taxed by IN |
| Retirement income | Up to $31,110 qualifying exclusion | Taxed at state + county rate; no exclusion (military retirement fully deductible) |
| Property taxes | Local rates + KY homestead exemption | 1% homestead cap + up to $150 Over 65 Credit |
| Healthcare | Strong Louisville network | Access to Louisville healthcare plus local providers |
| Housing | Wide range of price points | Wide range of price points |
| Commute / access | Louisville-centered | Easy access to Louisville from many communities |
| Best comparison | Total housing + tax cost, not the headline rate alone | |
A $20,000 difference in purchase price, plus a different property-tax bill, insurance cost, and maintenance load, can outweigh a relatively small difference in state income tax.
What About Shepherdsville and Elizabethtown?
Retirement doesn't have to mean living directly in Louisville. Shepherdsville can appeal to retirees who want to stay within the Louisville area while considering a different housing environment and access pattern. Elizabethtown offers a smaller-city setting while remaining within reach of Louisville and regional transportation routes. Neither is automatically cheaper: September 2026 median sale prices were $320,000 in Shepherdsville and about $316,000 in Elizabethtown, vs. $280,000 in Louisville (Flexmls). Shepherdsville’s property tax rate is lower, about $1.10 per $100 vs. about $1.25 inside Louisville’s Urban Services District; see Shepherdsville vs. Louisville costs and where retirees actually save around Louisville.
The right fit depends on what you're optimizing for: healthcare access points toward the Louisville metro and proximity to major medical facilities; reducing housing expense means comparing actual purchase price, taxes, insurance, and maintenance across all four areas; simplifying lifestyle means looking closely at home size, stairs, yard maintenance, and proximity to everyday services; and preserving home equity means thinking about resale demand before buying a highly specialized property.
Should You Buy a Home in Kentucky Before Retirement?
Not necessarily. Buying ahead of retirement can make sense if you plan to stay for many years, the payment fits comfortably within projected retirement income, you have sufficient liquid savings, the property will remain usable as you age, and the location has reasonable resale flexibility.
Renting may make more sense if you're unsure where you want to settle, you're testing Louisville against Southern Indiana, you expect to move again within a few years, or buying now would consume too much of your liquid retirement assets. If you do move toward a purchase, it helps to understand the process first: see how long it typically takes to buy a home in Louisville.
One of the biggest mistakes retirees make is becoming house-rich and cash-poor. Selling a $500,000 home and buying a $300,000 home could release roughly $200,000 of equity before transaction costs and other adjustments, capital that may carry more value as liquid reserves than as additional square footage.
Weighing whether to buy now, rent, or downsize before you retire? Let's run the numbers on your specific situation.
Start Your Home SearchDownsizing Can Be a Financial Strategy
Downsizing is often framed as a lifestyle decision, but it's also a balance-sheet decision. A large home with high property taxes, expensive insurance, significant maintenance, unused bedrooms, a large yard, and a mortgage carries real recurring cost. Moving into a smaller, easier-to-maintain home can reduce that cost while releasing equity, though selling costs, moving expenses, repairs, and the price of the replacement home all factor in.
Compare current total annual housing cost against future total annual housing cost plus the equity released.
That's a more useful calculation than simply asking how many bedrooms you need.
A Better Retirement Location Checklist
Before choosing Kentucky, Louisville, Southern Indiana, or another state, work through these eight categories in order:
| 1 | Housing costCalculate the full monthly cost, not just the listing price. |
| 2 | TaxesState income tax, property taxes, sales tax, and applicable local taxes. |
| 3 | HealthcareIdentify the hospitals, specialists, and services you're likely to use. |
| 4 | InsuranceGet actual homeowners insurance quotes before buying. |
| 5 | MaintenanceEstimate the annual cost of maintaining the property. |
| 6 | Resale flexibilityWould this property appeal to a broad range of buyers if your plans change? |
| 7 | AccessibilityStairs, bathrooms, entrances, parking, and future mobility needs. |
| 8 | LiquidityKeep enough cash reserved for healthcare, emergencies, travel, and investing. |
So, Is Kentucky a Good State to Retire In?
Kentucky can be a good retirement state, particularly for retirees who value housing affordability, favorable retirement-income tax treatment, and access to major healthcare in metropolitan areas. But the answer depends heavily on where in Kentucky you live and how your finances are structured.
Rather than stopping at "is Kentucky good for retirement," it's worth comparing Louisville, Southern Indiana, Shepherdsville, and Elizabethtown directly, using your actual retirement income, home budget, taxes, insurance, healthcare needs, and long-term housing plans. That comparison will tell you more than any national ranking.
Frequently Asked Questions
Is Kentucky tax-friendly for retirees?
Yes, for most retirees. Kentucky doesn't tax Social Security, excludes the first $31,110 per person of pension, IRA and 401(k) income, and taxes the rest at a flat 3.5% (2026). A couple with $70,000 of pension and IRA income split evenly pays about $272 a year. Investment income such as dividends and capital gains doesn't get the exclusion.
What is the best place to retire in Kentucky?
There's no single best place for every retiree. Louisville tends to suit people prioritizing healthcare access and housing variety, while Shepherdsville and Elizabethtown offer different housing options. The right choice depends on budget, healthcare needs, lifestyle, and long-term plans.
Is Louisville, KY a good place to retire?
Louisville can be a strong option for people who want access to major healthcare systems, a range of housing, and metropolitan amenities without moving to a much larger, higher-cost market. Healthcare and housing access should still be evaluated at the neighborhood and property level.
Is Kentucky or Indiana better for retirement?
It depends on your income mix. Retirees with pension or IRA income usually come out ahead in Kentucky: a 65+ retiree with $40,000 of pension income pays about $311 in Kentucky vs. about $1,881 in Clark County, Indiana (2.95% state plus 2.0% county). Retirees living on Social Security alone usually come out ahead in Southern Indiana, where the 1% homestead cap keeps property tax on a $350,000 home about $700 a year lower.
Does Kentucky have a property tax break for seniors?
Yes. The Kentucky homestead exemption takes $49,100 off the assessed value of a primary home for owners 65 or older or totally disabled (2025-2026). That's about $614 a year in Louisville and about $542 in Shepherdsville. You file once with your county PVA.
Should retirees downsize before retirement?
Downsizing can make sense when it reduces recurring housing costs, maintenance, and unused space while releasing meaningful equity. Selling costs, replacement-home prices, taxes, insurance, and future resale flexibility should all be weighed first.
Related Reading
| Kentucky vs. Indiana Retirement: Which State Is Better for Retirees? A deeper side-by-side on taxes, prices, and resale. |
| Kentucky Retirement Tax 2026: First $31,110 Is Tax-Free Exactly what Kentucky taxes, with worked examples. |
| Kentucky Homestead Exemption 2026: $49,100 Off for 65+ Who qualifies, what it saves and how to file. |
| Indiana Retirement Tax 2026: Social Security Free, Pensions Taxed The Indiana side, with county rates. |
| Louisville Housing Market: October 2026 Update Current prices, inventory and rates. |
| How Long Does It Take to Buy a Home in Louisville, KY? What to expect once you move from research to an offer. |
| Top Home Renovation Trends for 2026 in Louisville, KY Updates that support long-term value and accessibility. |
| Browse Louisville Homes for Sale See what's currently available across the metro. |
If you're weighing a retirement move to Louisville, Southern Indiana, Shepherdsville, or Elizabethtown, a local comparison built around your actual numbers is the fastest way to a confident decision.
Explore Greater Louisville Real EstateTamara West
KY & IN Realtor, Epique – KY Area Leader
502-819-2211 | tamara@tamarawestrealtor.com | GreaterLouisvilleLiving.com
Your Realtor for Life.
- Kentucky Department of Revenue — retirement income, homestead exemption, property taxes: revenue.ky.gov
- U.S. Census Bureau — Kentucky housing and demographic data: census.gov/quickfacts
- Indiana Department of Revenue — 2026 income-tax rates and retiree treatment: in.gov/dor
- Norton Healthcare — Louisville and Southern Indiana network: nortonhealthcare.com
- Flexmls MLS market statistics — Louisville, Shepherdsville and Elizabethtown, residential, September 2026 (pulled October 2026)
- Indiana Department of Revenue — Departmental Notice #1, state and county income tax rates: in.gov/dor
- Kentucky Department of Revenue — 2025-2026 homestead exemption: revenue.ky.gov
Categories
Recent Posts

 Broker Associate License ID: 247867MEET TAMARA WEST
Your Louisville & Southern Indiana Real Estate Broker
Since 2000, Tamara West has worked in finance, mortgage lending, real estate investing, and brokerage. That background shapes how she works with clients: she looks past the price of a home to what it actually costs you every month, and whether that fits where you're headed financially, not just where you'd like to live.
Licensed in both Kentucky and Indiana and based in Louisville, Tamara works with buyers, sellers, and investors across Louisville, Southern Indiana, Shepherdsville, and Elizabethtown. She's C2EX Certified through the National Association of Realtors, an ethics and professionalism endorsement, and currently serves as KY Area Leader at Epique Realty.
"A house has a price. It also has a payment, taxes, insurance, and a plan behind it. My job is to make sure you're looking at all of it, not just the number on the listing."
Buying or selling a home is a financial decision as much as a personal one. Tamara's approach combines the strategic side (rate, taxes, true cost of ownership, timing) with the practical side of getting a deal done, so you're making the move with the full picture in front of you, not just the highlight reel.
Why Work with Tamara West?- In finance, mortgage lending, and real estate since 2000
- Licensed broker in Kentucky and Indiana
- C2EX Certified/Endorsed through NAR
- KY Area Leader, Epique Realty
- Advisor-first approach: price is never the whole story
- Serving Louisville, Southern Indiana, Shepherdsville, and Elizabethtown
Check out these articles next
GET MORE INFORMATION