Kentucky vs Indiana Retirement: Which State Is Better for Retirees?
Retirement Planning · Louisville KY & Southern Indiana
Kentucky vs Indiana Retirement: Which State Is Better for Retirees?
A financial framework for comparing taxes, healthcare access, and housing costs before deciding where to retire.
Kentucky tends to appeal to retirees who want access to Louisville's healthcare systems, amenities, and housing inventory. Indiana tends to appeal to retirees seeking lower property taxes and potentially lower housing expenses. Neither state is automatically better — the right choice depends on your retirement income, housing preferences, healthcare needs, and how long you plan to stay in the home.
Retirement isn't just about where you want to live. It's about how you want your money to work for you over the next 20 to 30 years.
After decades of working, saving, paying down debt, and building home equity, the goal shifts from accumulating wealth to preserving it. That transition changes how people evaluate where they live. For homeowners considering retirement in the Louisville region, a common question emerges: should you retire in Kentucky or Indiana?
The answer is rarely as simple as comparing home prices. Property taxes, healthcare access, insurance costs, retirement income, home maintenance, and long-term housing flexibility can all affect your quality of life and financial security. For many retirees, the decision comes down to choosing between Louisville, Kentucky and nearby Southern Indiana communities such as Jeffersonville, New Albany, and Clarksville. Both areas offer advantages — the key is understanding which location aligns best with your financial goals and retirement lifestyle.
| ~17-18% Share of KY and IN population age 65+ | $250K-$300K Typical Louisville-area median home price | $335K Projected value of a $250K home after 10 yrs at 3% appreciation |
Which state better supports the retirement lifestyle and financial future you want to create?
Not sure how Kentucky and Indiana stack up for your specific retirement plan?
Email TamaraWhy Retirement Housing Decisions Are Different
Many buyers focus on purchase price. Retirees should focus on monthly costs. A home that costs $25,000 less upfront may become more expensive over time if taxes, insurance, maintenance, or utility expenses are significantly higher. This is why retirement planning should involve evaluating the complete financial picture, not just the listing price.
Important factors include:
- Property taxes
- Homeowners insurance
- Utilities
- Healthcare accessibility
- Maintenance requirements
- Future resale potential
- Estate planning considerations
A retirement home should support both your lifestyle and your financial flexibility.
Kentucky vs Indiana: Comparing the Cost of Living
According to recent cost-of-living data, both Kentucky and Indiana typically rank below the national average for overall living expenses. Louisville remains significantly more affordable than many major metro areas, with median home prices often ranging around $250,000–$300,000 depending on market conditions, while many Southern Indiana communities offer comparable housing options with competitive pricing. One reason retirees frequently compare Kentucky and Indiana is affordability. While costs vary by city and neighborhood, both states generally offer a lower cost of living than many coastal markets — especially attractive for retirees relocating from states such as California, Illinois, New York, or Florida.
Those considering a move to the Louisville area may also find value in reading our guide to Moving to Louisville KY: A Smart Relocation Guide. For a full breakdown of how the two states compare beyond retirement — including income taxes, insurance, and commuting costs — see our companion piece, Louisville KY Cost of Living: Kentucky vs Indiana (2026). Many retirees discover that housing dollars often stretch further in Kentucky and Southern Indiana than in many major metropolitan areas — though affordability should be measured by monthly expenses rather than home price alone. For current pricing and inventory context, see the Louisville, KY Real Estate Market Report — August 2026.
Property Taxes Can Significantly Impact Retirement Budgets
Indiana's average effective property tax rate is often around 0.75%–0.85%, while Kentucky's average effective property tax rate is commonly closer to 0.80%–0.90%, though local assessments and exemptions can significantly affect actual tax bills. Property taxes are often one of the largest recurring housing expenses after retirement. A lower property tax bill may not seem significant in a single year, but over ten or twenty years, the difference can add up substantially — one reason Southern Indiana attracts many retirees. Communities such as Jeffersonville and New Albany often appeal to buyers looking to reduce ongoing housing costs while maintaining convenient access to Louisville.
For a deeper breakdown of this topic, review our article: Kentucky vs Indiana Property Taxes in 2026: What Buyers Should Know. Property taxes should never be evaluated in isolation, but they should absolutely be part of the retirement decision process.
Curious what your total monthly ownership cost would actually look like on each side of the river?
Explore Greater Louisville Real EstateHealthcare Access Matters More Than Most Retirees Expect
Adults age 65 and older represent roughly 17%–18% of Kentucky's population and approximately 17% of Indiana's population, making healthcare access and aging-in-place planning important considerations in both states. Taxes get a lot of attention. Healthcare often deserves more. As retirement progresses, access to hospitals, specialists, outpatient services, and healthcare networks becomes increasingly important. One advantage of the Louisville area is the concentration of healthcare resources available throughout the metro region.
Whether you choose Louisville, Shepherdsville, Elizabethtown, Jeffersonville, or New Albany, it's worth evaluating:
- Distance to hospitals
- Specialist availability
- Emergency care access
- Transportation convenience
- Long-term healthcare planning
Many retirees discover that healthcare accessibility has a greater impact on quality of life than small differences in tax rates.
Housing Options for Retirees
Retirement often brings changing housing priorities. Large homes that worked well during child-raising years may become less practical. Many retirees begin looking for:
- Single-level homes
- Patio homes
- Condominiums
- Lower-maintenance properties
- Homes with fewer stairs
- Properties closer to healthcare and services
Louisville offers a broad range of housing choices, from established neighborhoods to newer communities designed around convenience and accessibility. Southern Indiana also offers attractive housing opportunities, often at competitive price points. The right choice depends on lifestyle goals rather than simply choosing the lowest-priced property. Buyers weighing a newer, low-maintenance build against an established home may also find New Construction vs. Resale in Louisville, KY (2026 Guide) useful.
Should Retirees Downsize?
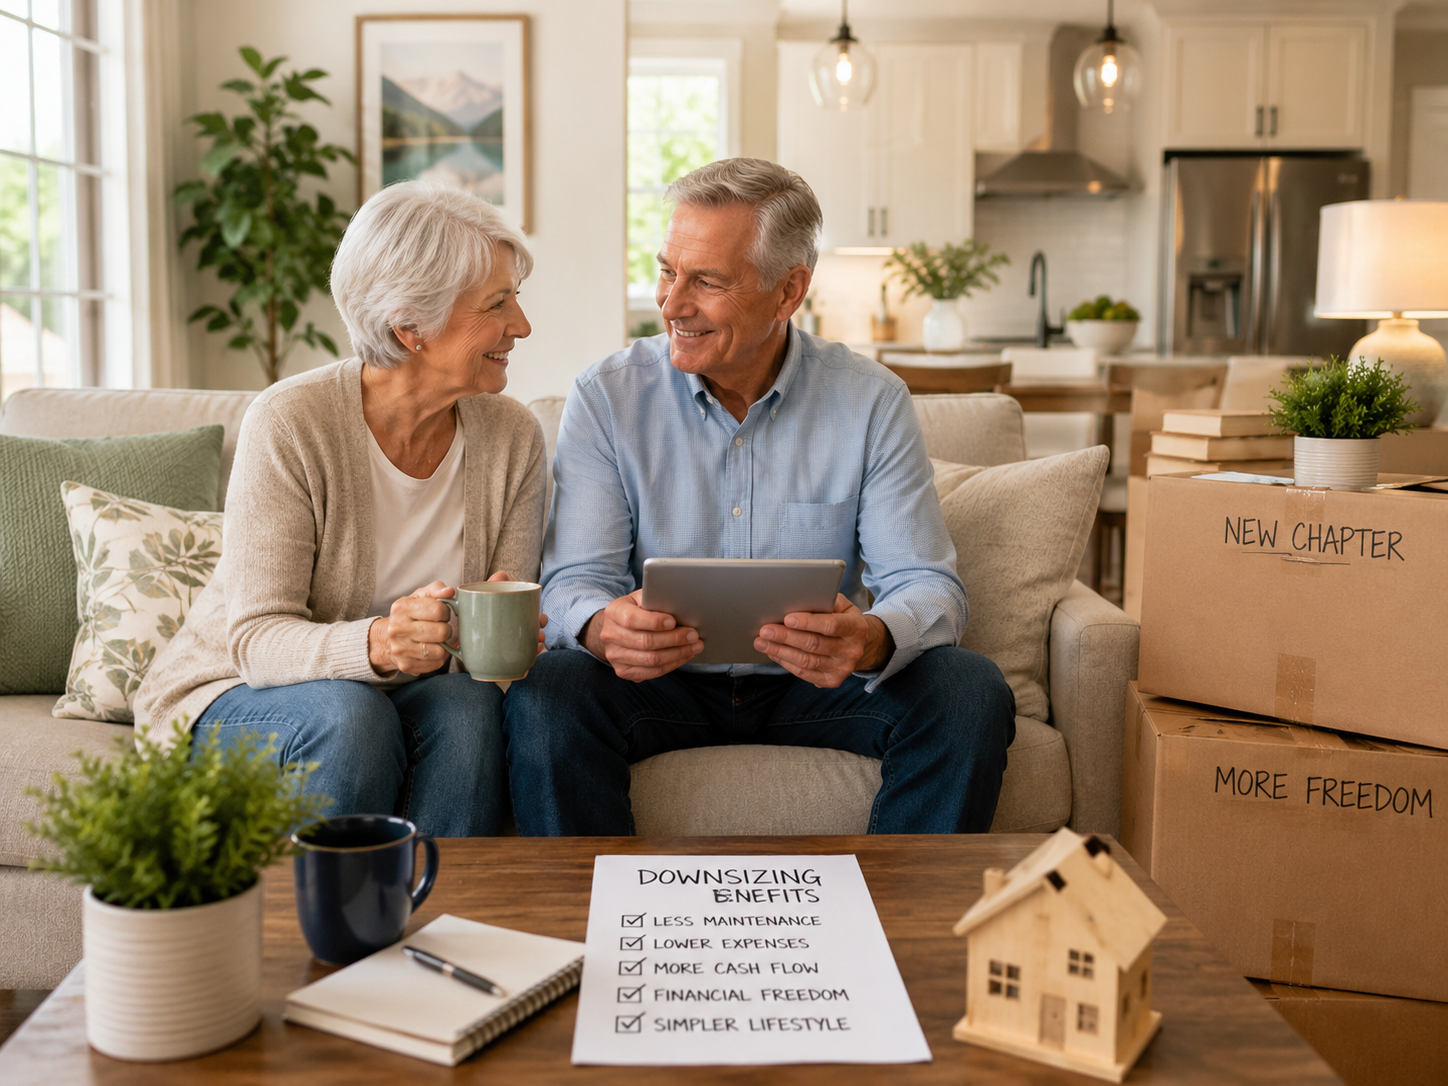
Many homeowners approaching retirement have accumulated substantial equity during the past decade. For example, a homeowner who purchased a $250,000 home and experienced 3% annual appreciation could potentially see their property value exceed $335,000 after ten years, creating opportunities to downsize and unlock equity. For many homeowners, downsizing can be one of the most effective retirement planning strategies. A larger home often contains significant equity that may be underutilized. Selling a larger property and purchasing a smaller, more manageable home can potentially:
- Reduce maintenance obligations
- Lower monthly expenses
- Improve cash flow
- Increase retirement reserves
- Simplify day-to-day living
Homeowners considering this approach may find additional insights in our article: Downsizing in Louisville: Turn Equity Into Income. For retirees exploring more affordable options after downsizing, Homes for Sale in Louisville KY Under $300K (2026 Guide) is a good starting point. Downsizing is not about sacrificing lifestyle — in many cases, it is about improving flexibility and financial security.
Kentucky vs Indiana Retirement Income Considerations
Retirement income often comes from multiple sources:
- Social Security
- Pensions
- Retirement accounts
- Investments
- Rental income
- Part-time work
The way income is taxed can influence retirement planning decisions. However, retirees should avoid making housing decisions based solely on tax considerations. A location that saves a small amount on taxes but increases healthcare costs, transportation expenses, or housing maintenance may not improve overall financial outcomes. The most successful retirement plans typically evaluate the full picture rather than focusing on a single financial variable.
Louisville vs Southern Indiana: Which Offers Better Long-Term Flexibility?
One factor many retirement articles overlook is future flexibility. Retirement is not a permanent finish line — plans change, health changes, family circumstances change, housing needs change. That is why resale potential matters. A retirement property should not only meet your current needs; it should also provide flexibility if you decide to move again in five, ten, or fifteen years.
Our guide to Louisville vs Southern Indiana: Where to Buy in 2026 explores some of these market differences in greater detail. When evaluating retirement housing, consider:
- Future buyer demand
- Community growth
- Accessibility
- Property maintenance requirements
- Market liquidity
These factors can influence how easily you can sell or transition later.
Kentucky vs Indiana Home Insurance Costs
Property taxes are only one piece of the affordability puzzle. Homeowners insurance can also affect retirement budgets, especially when living on fixed or semi-fixed income sources. Insurance premiums vary based on:
- Property value
- Age of the home
- Construction materials
- Claims history
- Coverage limits
- Location-specific risks
Retirees comparing Kentucky and Indiana should request insurance estimates before purchasing a home. Even a modest monthly difference can add up over years of ownership.
Monthly Cost = Mortgage (if any) + Taxes + Insurance + HOA Fees + Maintenance + Utilities
Many buyers focus heavily on list price while overlooking these recurring expenses.
Which Retirement Scenario Fits You?
Scenario 1: The Fixed-Income Retiree
For retirees relying primarily on Social Security, pensions, or retirement account distributions, predictability often matters more than growth potential. Priorities typically include stable housing expenses, lower maintenance obligations, healthcare accessibility, manageable property taxes, and convenient transportation. In this situation, a smaller home, patio home, condominium, or maintenance-friendly property may provide greater peace of mind than a larger property with higher ongoing expenses. The goal is not simply reducing costs — it is reducing financial surprises.
Scenario 2: The Active Retiree
Many retirees today remain highly active — they travel, volunteer, work part-time, care for grandchildren, or pursue hobbies. For these homeowners, convenience often becomes a major factor: How close are healthcare providers? How easy is airport access? How much home maintenance is required? Is the property suitable for aging in place? Louisville offers a broad range of amenities and healthcare resources, while Southern Indiana communities provide access to many of the same benefits with different housing and tax considerations.
Scenario 3: The Equity-Rich Homeowner
Many homeowners approaching retirement have accumulated substantial equity over the years. In these situations, retirement housing becomes both a lifestyle decision and a wealth-management decision — should you keep your current home, downsize, move closer to family, or free up equity for retirement income? For many homeowners, a strategic move can improve cash flow without reducing quality of life. This is where retirement planning overlaps with real estate strategy.
The Importance of Resale Flexibility
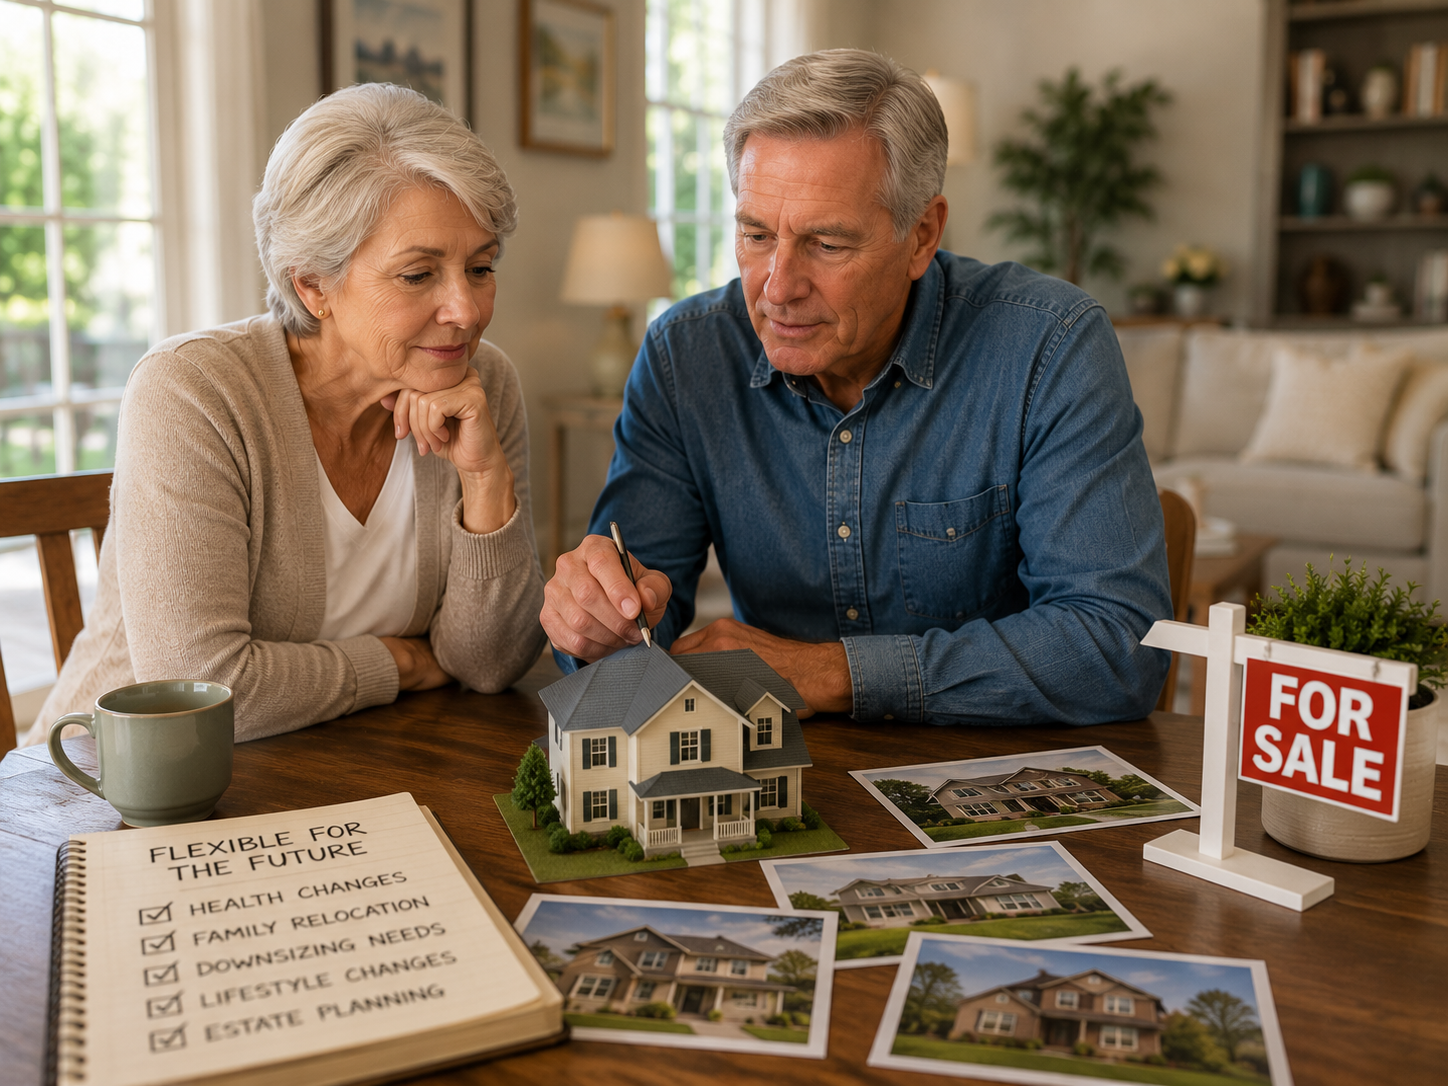
One mistake retirees sometimes make is purchasing a home that works today but may become difficult to sell later. Resale flexibility matters because retirement plans can change — health changes, family relocation, downsizing needs, lifestyle changes, and estate planning decisions are all common reasons retirees move again. When evaluating retirement housing, look beyond your immediate needs and ask: would this property still appeal to future buyers 10 years from now? Properties with broad market appeal often provide more flexibility and options later.
Shepherdsville vs Louisville for Retirement
Some retirees prefer living slightly outside Louisville while maintaining convenient access to city amenities. Shepherdsville is often considered because of its proximity to Louisville, access to major transportation routes, variety of housing options, and potential affordability advantages. For retirees seeking a balance between accessibility and value, Shepherdsville may be worth exploring as part of a broader retirement search strategy. The best fit depends on personal priorities rather than any single market statistic.
Elizabethtown as a Retirement Option
Elizabethtown continues to attract attention from retirees looking for a smaller-city environment, access to healthcare services, housing diversity, and regional connectivity. Some retirees appreciate the pace and scale of Elizabethtown while remaining within reach of Louisville when needed. Veterans considering this area may also want to review VA Loans Near Fort Knox: Elizabethtown & Radcliff Buying Guide. As with any retirement location, evaluating housing costs, healthcare access, and long-term flexibility is essential.
Common Retirement Mistakes Homeowners Make
Retirement housing decisions are often emotional. While emotions matter, financial considerations should remain part of the conversation.
| 1 | Buying Too Much HouseA larger home may create unnecessary maintenance and expense. |
| 2 | Ignoring Monthly CostsProperty taxes, insurance, utilities, and upkeep can have a greater impact than purchase price alone. |
| 3 | Focusing Only on TaxesTaxes matter, but healthcare access, convenience, and future flexibility often matter just as much. |
| 4 | Delaying PlanningWaiting until a major life event occurs can reduce available options. |
| 5 | Skipping Affordability AnalysisBefore making a move, homeowners should understand their complete financial picture. See How Much Home Can You Afford in Louisville KY 2026? for additional guidance. |
A Practical Kentucky vs Indiana Retirement Decision Framework
If you're struggling to choose between Kentucky and Indiana, consider evaluating each option using the same five-step framework.
| 1 | Calculate Total Monthly Housing CostsMortgage (if applicable), taxes, insurance, HOA fees, maintenance, and utilities. |
| 2 | Evaluate Healthcare AccessHospital proximity, specialists, transportation, and future care needs. |
| 3 | Consider Lifestyle PrioritiesFamily proximity, travel, recreation, and community involvement. |
| 4 | Evaluate Future FlexibilityCould this home support aging in place? Would it be easy to sell later? Does it fit long-term goals? |
| 5 | Align Housing With Retirement StrategyThe best retirement home is not necessarily the cheapest — it's the one that best supports your financial goals, lifestyle needs, and future flexibility. |
Kentucky vs Indiana Retirement Comparison: Key Takeaways
| Factor | Kentucky | Indiana |
|---|---|---|
| Property Taxes | Moderate | Often Lower |
| Cost of Living | Below National Average | Below National Average |
| Healthcare Access | Strong Around Louisville | Strong Near Louisville Metro |
| Housing Inventory | Larger Selection | Strong Value Opportunities |
| Retirement Flexibility | High | High |
| Access to Louisville Amenities | Excellent | Excellent |
There is no universal winner. The better choice depends on your income sources, housing goals, healthcare priorities, and long-term plans.
Final Thoughts
Retirement is about more than finding a place to live. It is about creating a lifestyle that supports financial stability, flexibility, and peace of mind. For some retirees, Kentucky provides the right combination of housing options, healthcare access, and community amenities. For others, Southern Indiana offers compelling advantages through lower property taxes and attractive housing opportunities. The most successful retirement decisions typically come from evaluating the complete financial picture rather than focusing on a single factor.
If you're considering retirement in Louisville, Shepherdsville, Elizabethtown, Jeffersonville, New Albany, or elsewhere in Southern Indiana, taking a strategic approach today can help create more options tomorrow.
Frequently Asked Questions
Is Kentucky or Indiana better for retirement?
Neither state is automatically better. The right choice depends on housing costs, taxes, healthcare access, lifestyle preferences, and long-term financial goals.
Does Indiana have lower property taxes than Kentucky?
Many Indiana communities have lower effective property tax burdens, which can reduce long-term housing expenses for retirees.
Is Louisville a good place to retire?
Louisville offers strong healthcare access, diverse housing options, cultural amenities, and a moderate cost of living, making it attractive for many retirees.
Should retirees downsize before retirement?
For many homeowners, downsizing can reduce monthly expenses, simplify maintenance, and unlock home equity that may support retirement goals.
What is the biggest financial factor retirees should consider when choosing where to live?
Total monthly housing costs — including taxes, insurance, maintenance, and utilities — often have a greater impact than purchase price alone.
Related Reading
| Louisville KY Cost of Living: Kentucky vs Indiana (2026) The full cost-of-living breakdown behind this retirement comparison. |
| Is Kentucky a Good State to Retire In? Pros & Cons (2026 Guide) A closer look at Kentucky specifically for retirees. |
| Kentucky vs Indiana Property Taxes in 2026: What Buyers Should Know A deeper dive into the property tax differences that affect retirement budgets. |
| Downsizing in Louisville: Turn Equity Into Income For retirees considering unlocking equity from a larger home. |
| Homes for Sale in Louisville KY Under $300K (2026 Guide) A starting point for retirees downsizing into a smaller budget. |
| Louisville vs Southern Indiana: Where to Buy in 2026 A broader market comparison beyond retirement-specific factors. |
| New Construction vs. Resale in Louisville, KY (2026 Guide) Helpful for retirees weighing a low-maintenance new build. |
| VA Loans Near Fort Knox: Elizabethtown & Radcliff Buying Guide For veteran retirees considering the Elizabethtown/Radcliff area. |
| How Much Home Can You Afford in Louisville KY 2026? A framework for affordability analysis beyond simple price ranges. |
| Louisville, KY Real Estate Market Report — August 2026 Current pricing and inventory data behind the affordability claims in this post. |
Ready to talk through what a Kentucky vs Indiana retirement move looks like for your specific situation?
Get in TouchTamara West
502-819-2211 | tamara@tamarawestrealtor.com | GreaterLouisvilleLiving.com
Your Realtor for Life.
- Greater Louisville Association of REALTORS® — local market context: glar.com
- Kentucky Department of Revenue — KY property tax reference: revenue.ky.gov
- Indiana Department of Revenue — IN property tax reference: in.gov/dor
- U.S. Census Bureau — population age 65+ figures: census.gov
- National Association of Realtors — national housing context: nar.realtor
Categories
Recent Posts
GET MORE INFORMATION